Guides · Points
Credit card bonus points: Australian sign-up exclusion periods in 2026
Compare Australian credit card sign-up bonus exclusion periods, including NAB, MyCard, Bankwest, ANZ, Westpac and Amex. Rules checked October 2026.
By Rewards That Fly · Updated 15 October 2026 · 9 min read
A credit card may advertise a sign-up bonus of 100,000 points or more, but that offer does not necessarily apply to every applicant.
Most Australian rewards card issuers exclude customers who currently hold, or have recently held, certain credit cards. The exclusion period varies by issuer and product, and some rules apply across several card families.
These periods have changed during 2026.
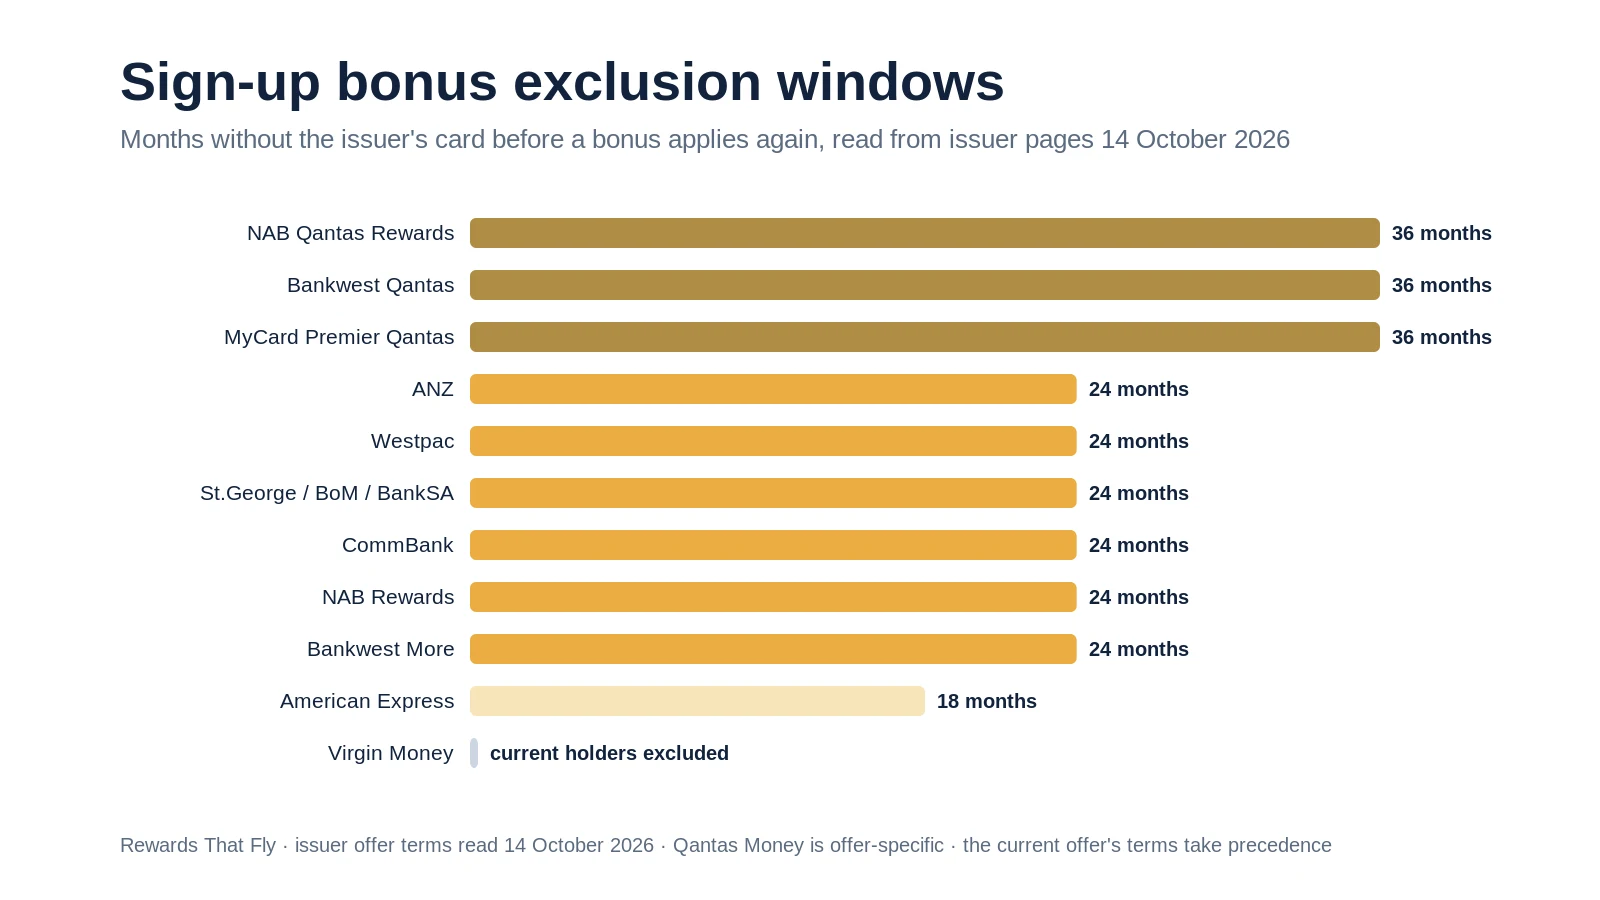
NAB Qantas Rewards, Bankwest Qantas Mastercard and MyCard Premier Qantas now have 36-month exclusions under their current offers. Many other major bank rewards cards use 24 months, while American Express generally applies an 18-month restriction.
The details matter. Some exclusions apply across several card products, while others distinguish between rewards families. A separate condition can also apply to an additional bonus even where the applicant qualifies for the standard offer.
We reviewed the available issuer terms on 14 October 2026. The table below summarises the current rules, including where further confirmation is needed.
At a glance
- 36 months: NAB Qantas Rewards, Bankwest Qantas Mastercard and MyCard Premier Qantas have the longest exclusions identified in our review.
- 24 months: ANZ, Westpac, CommBank, NAB Rewards and Bankwest More are among the major programs using two-year restrictions.
- 18 months: American Express generally applies an issuer-wide exclusion.
- Card families matter. ANZ Rewards and ANZ Frequent Flyer are treated together, while NAB distinguishes between its Rewards and Qantas Rewards families.
- The wording matters. Most restrictions concern cards held during a period. CommBank specifically refers to activated cards, while Qantas Money has an additional condition based on Qantas Points earned through other credit or charge cards.
- Older tables can be misleading. Several current offers differ from historical reference material.
The specific offer terms at the time of application take precedence over this guide. Meeting the exclusion-period requirement also does not guarantee approval or entitlement to a bonus.
Australian credit card sign-up bonus exclusion periods
The following table summarises the current published restrictions as at 14 October 2026.
| Issuer or card family | Exclusion period | Products covered | Verification |
|---|---|---|---|
| NAB Qantas Rewards | 36 months | Personal NAB Qantas Rewards cards | Issuer verified |
| Bankwest Qantas Mastercard | 36 months | Bankwest Qantas Mastercard accounts | Issuer verified |
| MyCard Premier Qantas | 36 months | MyCard Premier Qantas, subject to the current offer terms | Issuer verified |
| ANZ Rewards and Frequent Flyer | 24 months | Both ANZ rewards families | Issuer verified |
| Westpac rewards cards | 24 months | Specified Earth and Altitude products under the relevant offer | Issuer verified |
| St.George, Bank of Melbourne and BankSA | 24 months | Relevant Amplify products across the three brands | Issuer verified |
| CommBank Awards | 24 months | Relevant activated Awards cards held as primary cardholder, with product-switch exclusions | Issuer verified |
| NAB Rewards | 24 months | Personal NAB Rewards cards | Issuer verified |
| Bankwest More | 24 months | More Mastercard accounts under the current applicable offers | Issuer verified |
| American Express | Generally 18 months | Amex Australia-issued cards, subject to the particular offer | Issuer verified |
| Qantas Money | Offer-specific | Ordinary bonus conditions must be checked; an additional 24-month cross-issuer earning restriction applies to certain bonuses | Partially verified |
| Virgin Money | Current holders excluded | Existing Virgin Money credit cardholders, including upgrades | Issuer verified |
| G&C Mutual Bank | Not independently confirmed | Relevant rewards products | Further verification required |
Verification key
- Issuer verified: the relevant restriction was checked against current issuer material.
- Partially verified: a specific condition was confirmed, but a broader exclusion period remains unresolved.
- Further verification required: historical information exists, but the current issuer terms were not sufficiently established.
This table reports the exclusions applying to the offers reviewed. It should not be interpreted as a complete statement of every promotion offered by an issuer.
What about HSBC and Citi?
HSBC is no longer accepting new Australian retail banking applications. Its historical credit card exclusion periods have therefore been removed from the current-offer comparison.
Citi-branded Australian consumer cards transitioned to MyCard in November 2025. Current MyCard offers should be assessed under the applicable MyCard terms rather than relying on older Citi exclusion-period tables.
In particular, the current MyCard Premier Qantas offer contains a 36-month restriction.
The treatment of some legacy Citi account histories may require confirmation with MyCard. The change of brand should not be assumed to reset previous cardholding history.
What our October review found
The most material developments involve NAB, Bankwest and MyCard, alongside changes in how some other issuers describe their exclusions.
Several of these changes arrived in the weeks around the card surcharge ban that took effect on 1 October 2026. See what the surcharge ban has changed for Qantas and Velocity points earners.
NAB Qantas Rewards: 36 months
NAB's current Qantas Rewards offers apply a 36-month exclusion.
Our July 2026 review recorded a 24-month restriction, while the October terms state 36 months.
The current wording covers customers who currently hold, have held or are transferring from relevant personal NAB Qantas Rewards cards.
NAB Rewards remains a separate family with a 24-month lookback period.
However, the current offers also contain conditions relating to closing or transferring from other NAB credit cards. Being outside one family's lookback period does not establish eligibility on its own.
Bankwest Qantas Mastercard: 36 months
Bankwest's current Qantas Mastercard offer uses a 36-month exclusion.
Its More Mastercard offers use a separate 24-month restriction.
These are different rewards families, and the current offers also contain product-switch exclusions.
Older reference material showing 24 months for Bankwest Qantas should therefore not be relied upon without checking the current offer.
MyCard Premier Qantas: 36 months
MyCard's current Premier Qantas offer also applies a 36-month exclusion.
This is an important addition to the comparison because older Australian exclusion-period guides may still group the relevant products under Citi.
MyCard's current Premier Qantas offer commenced on 1 October 2026.
Other MyCard products may have different eligibility conditions, so the 36-month period should not automatically be applied across the entire portfolio.
CommBank: 24 months
CommBank's current offers apply a 24-month restriction to relevant activated Awards cards held as a primary cardholder.
The wording covers the specified Awards products, including Smart and Ultimate cards, and also includes product-switch restrictions.
This broader 24-month wording was present in offers earlier in 2026. It should not be described as a change introduced in October.
The distinction between activated cards and the period during which they were held is explained below.
Westpac: 24 months
Westpac's current rewards offers use a 24-month exclusion.
While some summary wording refers broadly to a Westpac credit card, the detailed terms identify particular Earth and Altitude products.
It would therefore be too broad to assume that every Westpac credit card is necessarily covered.
The specific list in the relevant offer determines the restriction.
How is the exclusion period measured?
The number of months is only one part of the rule.
The more important question in an individual case can be what event the issuer uses to measure eligibility.
1. Cards held during the lookback period
This is the most common approach.
An offer may exclude someone who:
Currently holds or has held an eligible credit card within the previous 24 months.
The restriction generally applies where the person held the relevant card at any point during that period.
Example: If an eligible card was closed 20 months ago, the former cardholder would generally remain excluded from a 24-month offer.
The relevant date is usually when the person stopped holding the card, rather than when the card was originally opened.
ANZ, Westpac, NAB and American Express use variations of this approach.
2. Activated cards
CommBank's wording refers to activated Awards cards held during the previous 24 months.
The word "activated" determines which previous accounts fall within the restriction.
It does not mean the 24-month period starts when the card was first activated.
For example, someone who activated a card three years ago but closed it six months ago would generally remain within a 24-month holding restriction.
A card that was approved but never activated may require clarification from CommBank, depending on the particular offer wording.
3. Previous bonus receipt
Some historical offers measured eligibility by when a previous sign-up bonus was received.
NAB previously used this approach before changing to a cardholding-based restriction.
That distinction matters because a bonus can be credited months after a card is opened.
A person should therefore not assume that an older bonus-receipt rule continues to apply to current offers.
4. Points earned through another credit or charge card
Qantas Money has an additional condition that can extend beyond its own card portfolio.
Its current Platinum offer includes an additional first-time Qantas Points earning cardholder bonus.
The relevant condition considers whether Qantas Points from any credit or charge card were credited to the applicant's Qantas Frequent Flyer account during the previous 24 months.
That period is measured from the application date.
It is separate from the ordinary eligibility conditions for holding a Qantas Money card.
A previous card issued by another bank may therefore affect eligibility for the additional bonus, even where the applicant otherwise qualifies for the standard Qantas Money offer.
This is an important reason to distinguish between an advertised total bonus and the portion a particular applicant may actually receive.
Which cards count as the same family?
A 24-month or 36-month rule is only meaningful when read together with the products it covers.
Some issuers combine several card products for bonus eligibility. Others maintain separate rewards families.
American Express
American Express generally applies its 18-month welcome-bonus restriction across cards issued by American Express Australia.
Previously holding one relevant Amex card can therefore affect eligibility for a bonus on another Amex product.
The precise scope still depends on the particular offer, including whether it contains additional restrictions.
ANZ
ANZ treats its Rewards and Frequent Flyer card families together for the relevant 24-month exclusion.
A former ANZ Frequent Flyer cardholder may therefore be excluded from an ANZ Rewards sign-up bonus, and vice versa.
Westpac and Amplify
Westpac's current rewards offers apply a 24-month restriction to the products identified in the relevant terms.
St.George, Bank of Melbourne and BankSA share the Amplify rewards platform, and their current offers explicitly cross-reference relevant products across those three brands.
However, common ownership does not mean every Westpac Group credit card belongs to one universal exclusion family.
Check the particular offer's list of covered products.
NAB
NAB distinguishes between two main personal rewards families:
- NAB Qantas Rewards: 36 months.
- NAB Rewards: 24 months.
The lookback clauses refer to the respective families.
Separate conditions concerning account closures and product transfers can also apply, so eligibility cannot be determined from the family distinction alone.
Bankwest
Bankwest also distinguishes between:
- Qantas Mastercard: 36 months.
- More Mastercard: 24 months under the current applicable offer.
Product-switch restrictions should be checked separately.
Qantas Money
Qantas Money's additional first-time Qantas Points earning bonus can be affected by points earned through cards issued by other banks.
This is different from a conventional same-issuer cardholding exclusion.
We could not independently confirm a general current 12-month former-Qantas-Money-cardholder restriction across the relevant offers.
For that reason, the main table does not present 12 months as a verified standing rule.
Other bonus conditions to check
Meeting the exclusion period does not guarantee that a sign-up bonus will be paid.
Other common requirements include:
New applications rather than upgrades. Product switches or upgrades may be excluded from a new-customer offer.
Primary cardholder status. Eligibility may depend on whether the person previously held a card as the primary account holder rather than as a supplementary cardholder.
Minimum eligible spending. Many bonuses require a specified amount of qualifying expenditure within a defined period.
Timing of bonus points. Points may be credited only after the relevant spending and account conditions are satisfied.
Offer-specific exclusions. A promotion may impose additional requirements beyond the issuer's general restrictions.
These conditions are separate from the credit approval process.
An applicant may satisfy a bonus exclusion rule and still not qualify for the product or the advertised bonus.
Why exclusion-period tables can become outdated
Our July and October reviews illustrate how quickly these rules can change.
NAB Qantas Rewards was shown at 24 months in our July review and 36 months in October.
Bankwest's current Qantas Mastercard offer also uses a longer period than older reference material.
Meanwhile, MyCard's current offers need to be assessed separately from historical Citi tables.
The published Australian Frequent Flyer exclusion-period reference remains useful for identifying historical rules and product families. However, its published version does not reflect every current issuer offer.
That is not a criticism of historical reference material.
It is a limitation of relying on information that can change between application periods.
The verification date is part of the data.
We review this guide quarterly and following material changes, but the current issuer terms should always be checked before an application decision.
How to use this guide
For anyone keeping records of points-earning cards, the most useful information to retain is:
- issuer and card product;
- the relevant rewards family;
- account opening date;
- account closing date;
- whether the card was activated; and
- any relevant bonus eligibility conditions.
Those details can help establish whether a published exclusion period may apply.
Before relying on the table, check the specific offer's current terms, including which products are covered and how the lookback period is measured.
Bonus eligibility and credit suitability are separate questions. Annual fees, interest rates, spending requirements, lending criteria and individual circumstances matter independently of the points offered.
This guide provides factual information about published exclusion conditions. It does not recommend credit cards or assess whether applying for credit is appropriate.
For broader points information, see our Qantas Frequent Flyer guide, Velocity Frequent Flyer guide and Points Valuations.
Our points transfer bonuses guide also explains how transfer promotions can affect the value of points held in participating bank and rewards programs.
Methodology and sources
Verification date
The issuer material used for this guide was reviewed on 14 October 2026.
The comparison focuses on published exclusion conditions for current or recently advertised Australian rewards credit card offers.
A listed period should not be interpreted as applying automatically to every product or promotion from the same issuer.
NAB
The current NAB Qantas Rewards terms state a 36-month exclusion for relevant personal NAB Qantas Rewards cards.
The NAB Rewards terms state a separate 24-month restriction.
Both product families can also have conditions concerning account closures and transfers.
Bankwest
The Bankwest credit cards page states a 36-month restriction for the Qantas Mastercard and a 24-month restriction for relevant More Mastercard offers.
Current offers also contain product-switch conditions.
MyCard
The MyCard website provides the current Premier Qantas offer, including its 36-month former-cardholder restriction.
Citi-branded Australian consumer cards transitioned to MyCard in November 2025.
The treatment of individual legacy Citi accounts should be confirmed with MyCard where relevant.
ANZ
The ANZ Frequent Flyer Black terms apply a 24-month exclusion across relevant ANZ Rewards and ANZ Frequent Flyer products.
Westpac and Amplify
The Westpac Altitude Qantas Black offer applies a 24-month restriction to the specified Earth and Altitude products.
Current St.George Amplify terms also contain a 24-month exclusion and cross-reference relevant products from St.George, Bank of Melbourne and BankSA.
The Westpac and Amplify restrictions should not automatically be treated as one universal Westpac Group exclusion.
CommBank
The CommBank credit cards page and relevant current product terms apply a 24-month lookback to specified activated Awards card types held by primary cardholders.
Product-switch exclusions also apply.
The activated-card wording identifies the previous accounts covered. It does not establish activation as the date from which the lookback period runs.
American Express
American Express's Membership Rewards and welcome-bonus guidance supports the general 18-month restriction.
Individual offer terms determine the applicable products and any additional exclusions.
Virgin Money
The Virgin Money credit card terms exclude existing Virgin Money credit cardholders, including upgrades.
No general former-cardholder exclusion period was identified in the wording reviewed.
The absence of a stated former-cardholder period does not establish guaranteed eligibility immediately after closing an account.
Qantas Money
The Qantas Money credit cards page contains the additional first-time Qantas Points earning cardholder condition.
It refers to Qantas Points credited from a credit or charge card within the previous 24 months.
We did not establish a single current 12-month ordinary cardholding exclusion that could safely be applied across all Qantas Money offers.
HSBC
HSBC's Australian retail banking notice states that new retail banking applications are no longer being accepted.
Historical HSBC sign-up bonus exclusion periods are therefore omitted from the current-offer comparison.
Secondary references and unresolved items
Australian Frequent Flyer's exclusion-period reference was reviewed for historical context.
The currently accessible version displays a publication date of 6 May 2025.
Some issuer rules have changed since that date.
We could not independently establish a current primary-source exclusion period for G&C Mutual Bank in this review. It remains in the comparison only as an unresolved item.
Change history
The changes identified between July and October reflect our archived observations of issuer wording, not necessarily the exact dates on which the issuers introduced the new restrictions.
The current NAB and MyCard offers include October 2026 commencement dates, but that does not establish the first date on which an issuer used a particular exclusion across every product.
Scope and limitations
This guide describes published sign-up bonus eligibility restrictions.
It does not assess individual eligibility, credit approval, product suitability or the overall value of a credit card.
Exclusion periods can differ between offers and may change without notice.
The current terms of the specific offer take precedence over this guide.
We review the guide quarterly and following material changes. Updates are recorded in the Program Change Log.